Porsche 911 Lease Guide: Residual Values, Allocation Realities & Money Factor Optimization
Master the 2026 Porsche 911 lease process. Learn how 992.2 Carrera allocations, industry-leading residual values, single-pay leases, and credit tiers work.
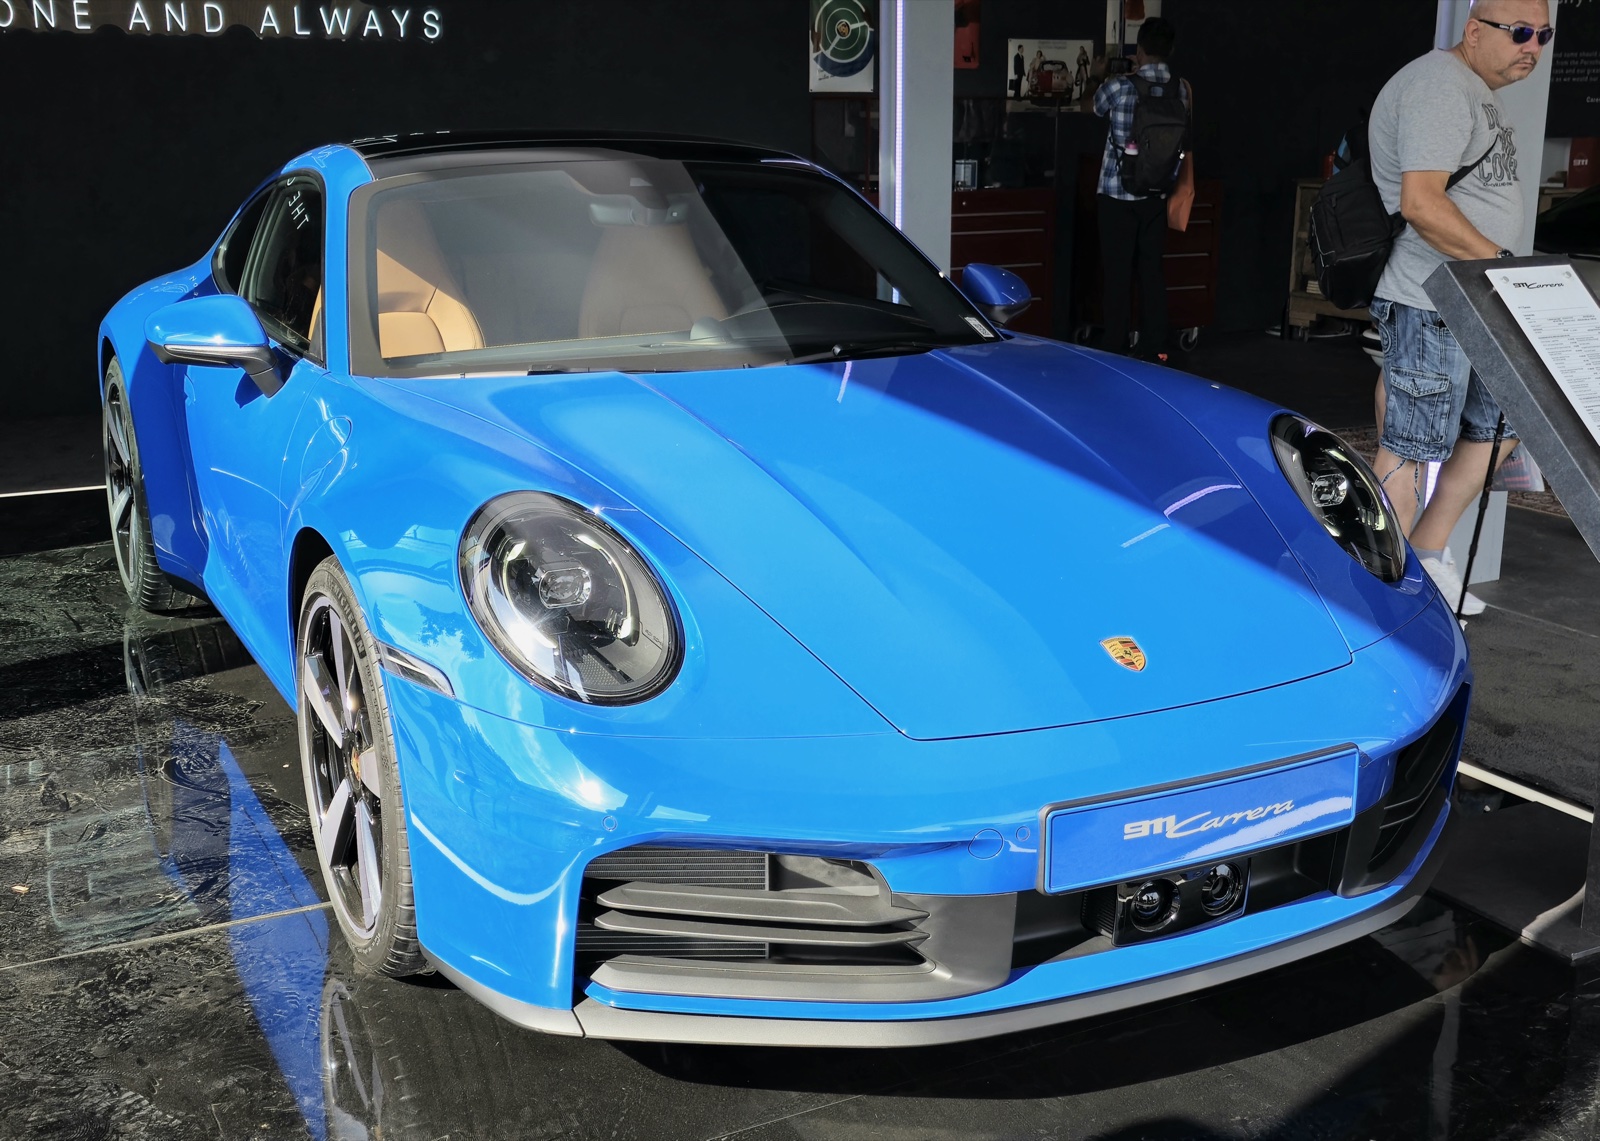
The Porsche 911 represents the benchmark against which every sports car on earth is measured. With the arrival of the refreshed 992.2 generation, featuring sharper digital cockpit integration, refined aerodynamics, and the groundbreaking T-Hybrid powertrain on the Carrera GTS, demand for Stuttgart's icon has reached historic highs.
However, leasing a Porsche 911 is unlike leasing an everyday family crossover. Porsche Financial Services (PFS) operates under unique guidelines, dealership allocation slots are tightly guarded, and residual values rank among the highest in the entire global automotive industry. Understanding these mechanics empowers enthusiasts to secure their dream sports car on favorable financial terms.
Navigating 992.2 Allocations and Model Variants
Securing a Porsche 911 begins with understanding dealer allocation mechanics. Authorized retail franchise stores receive limited factory build slots:
911 Carrera & Carrera 4
The baseline Carrera features an upgraded 3.0-liter twin-turbocharged boxer-6 engine generating 388 horsepower and 331 lb-ft of torque. Paired exclusively with Porsche's lightning-fast 8-speed PDK dual-clutch transmission, the Carrera reaches 60 mph in 3.9 seconds (3.7 seconds with the Sport Chrono Package) and tops out at 183 mph. For daily driving across New Jersey and New York, the Carrera 4 provides all-weather all-wheel-drive traction.
911 Carrera GTS: The T-Hybrid Era
The 992.2 Carrera GTS introduces Porsche's pioneering T-Hybrid system. Pairing a newly developed 3.6-liter boxer engine with an electric exhaust gas turbocharger and an integrated permanent magnet synchronous motor in the PDK gearbox, the GTS unleashes 532 horsepower and 449 lb-ft of torque. It rips from 0 to 60 mph in a blistering 2.9 seconds with zero turbo lag.
The Secret Weapon: Unmatched Residual Value Retention
Why does leasing a $130,000 Porsche 911 often cost less per month than leasing a similarly priced sports sedan? The answer lies in residual value retention.
Because secondary market demand for pre-owned Porsche 911 models remains voracious, Porsche Financial Services sets 36-month residual values exceptionally high, frequently between 66% and 72% on 5,000 to 10,000-mile annual leases. Because you only pay for the depreciation you consume during the lease term, a 911 with a 70% residual loses only 30% of its capitalized value over three years.
Hypothetical Depreciation Comparison: Porsche 911 vs Typical Luxury Rival
| Lease Parameter | 2026 Porsche 911 Carrera | Typical $130k Luxury Flagship |
|---|---|---|
| **Manufacturer MSRP** | $128,000 | $128,000 |
| **36-Month Residual Percentage** | 68% ($87,040 Residual Value) | 48% ($61,440 Residual Value) |
| **Total 3-Year Capital Depreciation** | $40,960 | $66,560 |
| **Monthly Depreciation Expense** | $1,137 / month | $1,848 / month |
| **Net Monthly Payment Advantage** | Substantially Lower Monthly Obligation | Much Higher Monthly Obligation |
Financial Structuring: Single-Pay Leases and Money Factor Reduction
For high-net-worth clients and business executives, Porsche Financial Services offers a Single-Pay Lease program that slashes borrowing costs.
By paying the entire 36-month lease term in a single upfront lump sum, PFS rewards the borrower by discounting the money factor by up to 0.00080 (equivalent to approximately 1.92% APR reduction). This strategy eliminates monthly payment administration, saves thousands of dollars in compounding finance rent charges, and preserves full GAP insurance protection in the event of an unforeseen total loss.
Tier 1 Credit Criteria and Approval Guidelines
Porsche Financial Services maintains rigorous underwriting standards:
1. **Credit Score Thresholds:** Optimal PFS tier 1 approval typically requires a FICO score of 740 or higher, with an established history of high-balance automotive financing.
2. **Debt-to-Income Ratios:** Lenders look for total debt-to-income ratios below 40%, ensuring sports car lease commitments do not strain cash flow.
3. **Corporate and LLC Guarantees:** Many 911 models are leased through corporate entities. PFS allows corporate leasing provided the principal owner acts as a personal guarantor with matching top-tier credit credentials.
Avoid Showroom Markups with Capital Motor Cars
Franchise dealerships frequently demand predatory dealer markups (ADMs) of $10,000 to $30,000 over MSRP on 911 build allocations. Capital Motor Cars works directly with multi-state corporate dealer networks to locate true MSRP allocation slots and negotiate bank buy-rate financing. Let our concierge team manage your custom factory order or locate immediate inventory for white-glove doorstep delivery.
Frequently Asked Questions
Can I build and custom-order a Porsche 911 through Capital Motor Cars?
Yes! Our auto broker team works with nationwide franchised Porsche partners to locate open production allocation slots. You receive an official Porsche build code, configure your exact options, and track factory manufacturing from start to finish.
Does a Porsche 911 lease include factory warranty coverage?
Every new Porsche 911 includes a 4-year or 50,000-mile factory limited warranty. When signing a 36-month lease, your entire driving tenure is 100% covered under original manufacturer bumper-to-bumper warranty protection.
Can I sell or trade my Porsche 911 before the lease term ends?
Yes. Porsche Financial Services allows lease buyouts and trade-ins at any authorized dealership. Because 911s preserve equity so effectively, many drivers exit their leases early with positive equity that can be cashed out or applied toward their next vehicle.
Related Automotive Guides & Lease Specials
2026 Mercedes-Benz E-Class Lease Review: W214 E 350 vs E 450 4MATIC Luxury Sedan Deals
Detailed 2026 Mercedes-Benz E-Class lease guide. Compare W214 E 350 and E 450 4MATIC models, MBUX Superscreen tech, mild-hybrid specs, and corporate lease deals.
Car ReviewsSingle-Pay Car Lease Guide: How Paying Upfront Cuts Money Factor Interest & Eliminates Monthly Bills
Discover how a single-pay (one-pay) car lease works. Learn how paying upfront discounts captive money factors, eliminates compounding interest, and saves thousands.
Car ReviewsBMW M3 & M4 Competition xDrive Lease Guide: Allocations, Money Factors & High-Performance Terms
Learn how to lease a 2026 BMW M3 or M4 Competition xDrive. Master dealer allocations, BMW Financial money factors, maintenance inclusion, and zero markup terms.
Car Reviews2026 Rivian R1S Electric SUV Lease Guide: Dual-Motor vs Tri-Motor Specs, NJ Tax Rebates & Residual Values
Complete 2026 Rivian R1S lease guide. Learn how New Jersey EV sales tax exemptions, federal lease credits, Dual-Motor vs Tri-Motor specs, and high residuals reduce monthly costs.